Tax Code S0T Explained: What It Means for Your Pay in Scotland?

Last Updated – 02-11-2026
The S0T tax code means that your employment or pension income is taxed using Scottish Income Tax rates, with no tax-free Personal Allowance allocated to that particular income source.
You might see S0T on your payslip after starting a new job, taking on additional employment, receiving a pension or when HM Revenue and Customs (HMRC) does not have enough information to calculate your normal tax code.
For the 2026/27 tax year, the standard UK Personal Allowance remains £12,570.
However, someone with S0T does not receive that allowance against the income covered by the code, meaning Income Tax can be deducted from the first pound of taxable pay.
This does not necessarily mean you have lost your Personal Allowance altogether or that HMRC has made a mistake. Your allowance may already be allocated to another employment or pension.
Understanding how S0T works is important because Scottish Income Tax has six rates, ranging from 19% to 48%, and an incorrect tax code could affect your take-home pay considerably.
What Does the S0T Tax Code Mean?
S0T is a PAYE tax code used for individuals treated as Scottish taxpayers who have no Personal Allowance allocated to a particular employment or pension.
The code can be broken down into three components.
| Code element | Meaning |
| S | Scottish Income Tax rates apply |
| 0 | No tax-free allowance is allocated to this income source |
| T | Forms part of the special 0T code, used when no allowance is available or sufficient coding information is missing |
The S prefix tells the employer or pension provider to apply Scottish Income Tax bands rather than the rates used in England, Wales or Northern Ireland.
The 0T element means that the PAYE calculation does not deduct a Personal Allowance from the taxable income covered by that code.
Under HMRC’s explanation of what tax codes mean, S0T can be used when the Personal Allowance has been exhausted or when a new employer lacks the information required to determine the appropriate tax code.
For example, someone employed full-time in Edinburgh might have S1257L on their main job and S0T on another income source if HMRC considers that the latter should be taxed using Scottish bands without a separate allowance.
The distinction matters: the code determines the tax treatment of a particular income source, not necessarily the person’s final Income Tax liability across all sources.
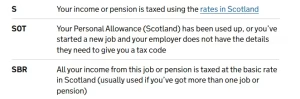
HMRC confirms that S0T applies where a Scottish taxpayer has no Personal Allowance available for a job or pension, or where sufficient employment information is missing.
Why Have You Been Given the S0T Tax Code?
There are several reasons HMRC or an employer may use S0T. Some are temporary administrative circumstances, while others reflect the taxpayer’s actual income position.
Starting a New Job Without Complete Tax Information
When someone changes employment, their new employer normally needs details of their previous income and tax payments.
These are commonly provided through a P45.
If the required details are unavailable, payroll may initially operate a temporary code while the employee’s PAYE information is established.
For example, someone leaving a Glasgow employer in September and beginning another job in October may encounter a coding problem if their previous employment details have not been recorded correctly.
The employee should provide their P45 where available or complete the appropriate HMRC starter checklist.
It is important to understand that a missing P45 does not automatically require S0T. The initial code depends on the applicable starter procedures and HMRC instructions.
Employees who cannot locate their documents can find further information about getting a copy of their P45 from HMRC.
Having More Than One Job
HMRC may allocate the full Personal Allowance to one employment and no allowance to another.
Consider someone with two jobs:
| Income source | Annual income | Illustrative code |
| Main employment | £32,000 | S1257L |
| Second employment | £9,000 | S0T |
| Total employment income | £41,000 | Two separate PAYE codes |
In this illustrative arrangement, the main employment receives the standard allowance and the second employment receives none.
However, S0T is not the only code HMRC can use for a second job. SBR or another Scottish rate code may be more appropriate depending on the person’s total earnings and the allocation of tax bands.
The employer should use the authorised code rather than select whichever appears to produce the most favourable deduction.
Receiving More Than One Pension
People with multiple private or occupational pensions can also receive S0T.
One pension may receive an allocated Personal Allowance while another is taxed without it.
The same issue can arise where an individual receives employment income alongside pension income.
Having a Reduced or Exhausted Personal Allowance
The UK Personal Allowance starts reducing when adjusted net income exceeds £100,000.
For every £2 of adjusted net income above that threshold, £1 of the allowance is withdrawn.
At adjusted net income of £125,140, the standard Personal Allowance is fully removed.
Therefore, an individual with sufficiently high income may legitimately receive a zero-allowance code.
Our analysis suggests that readers should distinguish this situation from temporary missing-employment-information cases. Both may produce S0T, but the reasons and corrective actions differ substantially.
What Are the S0T Tax Rates in Scotland for 2026/27?
S0T does not apply a single flat tax rate.
Instead, taxable employment or pension income moves through the relevant Scottish tax bands.
For the period from 6 April 2026 to 5 April 2027, the Scottish Income Tax rates are:
| Scottish tax band | Rate | Income range with standard £12,570 allowance |
| Personal Allowance | 0% | £0–£12,570 |
| Starter | 19% | £12,571–£16,537 |
| Basic | 20% | £16,538–£29,526 |
| Intermediate | 21% | £29,527–£43,662 |
| Higher | 42% | £43,663–£75,000 |
| Advanced | 45% | £75,001–£125,140 |
| Top | 48% | Above £125,140 |
These are the standard published ranges, assuming the full Personal Allowance. The rates are confirmed in the Scottish Government’s current Income Tax guidance.
How the Bands Work Without an Allowance?
An important distinction is that S0T does not provide the normal £12,570 tax-free starting amount.
The underlying Scottish rate bands are applied to taxable income without that allowance.
For a simplified annual calculation, the taxable-income bands are:
| Taxable income under S0T | Rate |
| First £3,967 | 19% |
| £3,967–£16,956 | 20% |
| £16,956–£31,092 | 21% |
| £31,092–£62,430 | 42% |
| £62,430–£125,140 | 45% |
| Above £125,140 | 48% |
This distinction prevents a common calculation mistake: applying the standard income thresholds, which already include the Personal Allowance, to someone who has no allowance in their code.
Ellen Milner, Director of Public Policy at the Chartered Institute of Taxation, highlighted the effect of frozen higher thresholds in her April 2026 commentary:
“Taxpayers may see their own tax liabilities increase as wages grow and tax thresholds higher up the income scale remain frozen.”
Her observation reinforces why understanding which Scottish bands apply is important, particularly for employees whose income changes during the tax year.
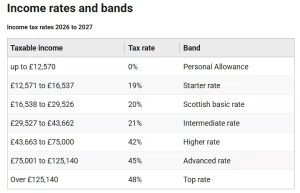
Scottish Income Tax rates for 2026/27 range from 19% to 48%, with the standard published thresholds assuming the Personal Allowance.
How Much Tax Will You Pay on S0T?
The amount of Income Tax deducted under S0T depends on taxable income, pay frequency and whether the code is operated cumulatively or on a Week 1/Month 1 basis.
To illustrate the impact, we calculated approximate annual Income Tax liabilities under S0T and compared them with S1257L for an employee receiving the full standard allowance.
| Annual gross taxable salary | Annual Income Tax: S0T | Annual Income Tax: S1257L |
| £20,000 | £3,990.77 | £1,446.33 |
| £30,000 | £6,090.77 | £3,451.07 |
| £40,000 | £10,061.45 | £5,551.07 |
These are illustrative full-year Scottish Income Tax calculations for one employment, assuming constant taxable salary, no other coding adjustments and entitlement to the full allowance in the S1257L comparison.
They exclude National Insurance, pension contributions, salary sacrifice and other deductions. Actual PAYE deductions may differ.
Example: S0T on a £30,000 Salary
Suppose an employee earns £30,000 annually and their income is taxed under S0T.
The illustrative annual calculation would be:
- First £3,967 at 19% = £753.73
- Next £12,989 at 20% = £2,597.80
- Remaining £13,044 at 21% = £2,739.24
Total annual Income Tax: £6,090.77
That represents approximately £507.56 per month in Income Tax when annual deductions are averaged across twelve months.
By comparison, an employee with the same £30,000 salary and the full allowance under S1257L would have an illustrative annual Income Tax liability of £3,451.07.
The difference is approximately £2,639.70 annually.
However, this does not mean that everyone on S0T is overpaying by that amount.
If the Personal Allowance has already been used against another employment or pension, applying it again would be incorrect.
Our calculation demonstrates the potential impact of receiving no allowance against a particular salary, not a guaranteed tax refund.
Is S0T an Emergency Tax Code?
S0T is not automatically an emergency tax code.
Although S0T can appear during periods when HMRC lacks complete employment information, the code itself is not necessarily operated on an emergency basis.
HMRC identifies emergency tax treatment through markers such as:
| Payslip code | Meaning |
| S0T | No Personal Allowance allocated; not automatically emergency |
| S0T W1 | S0T operated on a Week 1 basis |
| S0T M1 | S0T operated on a Month 1 basis |
| S0T X | Non-cumulative emergency treatment |
| S0T NONCUM | Non-cumulative treatment shown by some payroll systems |
A cumulative tax code normally takes account of relevant earnings and tax already recorded during the tax year.
A Week 1 or Month 1 code generally calculates PAYE using the current pay period without taking the full earlier-year-to-date position into account.
For example, someone earning £2,500 in a month under S0T M1 would normally have that month’s taxable pay assessed using monthly portions of the Scottish tax bands, without applying a Personal Allowance.
The deduction may be different from that under a cumulative code where previous payments and tax deductions are taken into account.
Employees uncertain about these differences can review how an emergency tax code affects pay.
What Is the Difference Between S0T, S1257L and SBR?
These codes are all associated with Scottish Income Tax, but they instruct employers to calculate PAYE differently.
| Tax code | Meaning | Personal Allowance allocated? |
| S1257L | Scottish rates with standard allowance | Usually £12,570 |
| S0T | Scottish rates, no allowance, progressive bands | No |
| SBR | All income from that source taxed at Scottish basic rate | No |
| SD0 | Income taxed at Scottish intermediate rate | No |
| SD1 | Income taxed at Scottish higher rate | No |
| 0T | No allowance; non-Scottish PAYE bands | No |
| C0T | Welsh rates, no allowance | No |
The difference between S0T and SBR is particularly important.
SBR generally applies the 20% Scottish basic rate to all taxable income from the relevant employment or pension.
S0T, by comparison, uses the applicable progressive Scottish rate bands.
This means an S0T taxpayer can have income taxed at 19%, 20%, 21%, 42%, 45% or 48%, depending on the taxable amount.
For further context, understanding whether BR is an emergency tax code helps explain why a flat-rate code and a non-cumulative PAYE marker serve different purposes.
Can S0T Apply to a Payment After Leaving a Job?
Yes. This is an important circumstance that is often overlooked when explaining S0T.
HMRC’s employer payroll instructions confirm that where an employee has already received a P45 but subsequently receives another taxable payment from their former employer, the employer may need to use S0T on a non-cumulative basis if the employee was previously on a Scottish tax code.
Such payments can include outstanding wages, certain bonuses, taxable holiday pay or other post-employment payments.
For example, an employee might leave a company in Aberdeen in August and receive their P45.
If the former employer later pays a taxable bonus in October, S0T may be required for that payment, even though the employee has already left the business.
This does not automatically mean that the employee’s Personal Allowance has disappeared from their wider tax position.
It is a specific payroll treatment required for certain payments made after leaving.
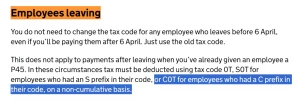
HMRC’s 2026/27 payroll instructions explain when employers must use S0T on a non-cumulative basis for payments after a Scottish employee has left.
How Can You Check Whether Your S0T Tax Code Is Correct?
The first step is to compare the code on your payslip with the information HMRC holds about your employment and pensions.
You can find your tax code through your payslip, HMRC’s online Income Tax service, the HMRC app or a tax-code notice.
When reviewing S0T, check the following:
- Current employment: Confirm that HMRC has recorded your existing jobs correctly.
- Previous employment: Check whether an old employment is still incorrectly marked as active.
- Personal Allowance: Identify which job or pension is receiving your allowance.
- Estimated income: Check that HMRC’s annual income estimates reflect your circumstances.
- Pension income: Confirm that any private, occupational or State Pension information is accurate.
- Scottish tax status: Check that HMRC has your correct main residential address.
- Payroll details: Make sure your employer is using the latest authorised tax code.
A P45 or P60 can help establish previous earnings and tax payments. Readers can also compare the information recorded in these documents through the explanation of P60 vs P45.
If S0T appears on your only employment and you believe you should receive the standard Personal Allowance, you should investigate rather than assume the code is correct.
Equally, if it is attached to a second employment, pension or post-leaving payment, it may have a legitimate explanation.
How Can You Change the S0T Tax Code If It Is Wrong?
If HMRC has incorrect information, you can request a correction through its online Income Tax service.
The process generally involves reviewing employment details, updating inaccurate income estimates and confirming which sources of income are still active.
Steps to Correct the Code
- Sign in to your HMRC Personal Tax Account or use the HMRC app.
- Check the tax code and income information for the current tax year.
- Review your jobs, pensions, taxable benefits and estimated income.
- Correct inaccurate or outdated information.
- Provide your P45 to your new employer where applicable.
- Check whether HMRC issues a revised coding notice.
- Compare the updated code with your next payslip.
HMRC currently says that, where a tax-code change is necessary, it normally updates the code and informs the taxpayer and employer within 15 working days.
For monthly-paid employees, the updated code should generally appear on the next or following payslip. Weekly-paid employees should normally see the change by their third payslip.
If you recently started a new job, HMRC recommends allowing up to 35 days from the start of employment for the necessary information to be received before contacting it about an unresolved code.
An employer cannot ordinarily change an existing HMRC-issued code simply because the employee requests a different one. Payroll must follow the applicable HMRC instructions and starter rules.
Will You Get a Tax Refund If S0T Was Wrong?
You may receive an Income Tax refund if S0T caused more tax to be deducted than you actually owed.
The refund depends on your total taxable income, allowances and tax already paid.
If HMRC issues a corrected cumulative code during the tax year, your employer or pension provider may be able to make the appropriate adjustment through payroll.
A refund can therefore sometimes appear in a later payslip without a separate application.
However, if the tax year has ended, HMRC may need to reconcile your PAYE records before confirming whether you have overpaid.
In some cases, this involves a P800 tax calculation.
Anyone awaiting an end-of-year reconciliation can read more about when HMRC issues P800 tax refunds.
It is important not to assume that every S0T deduction creates a refund entitlement. Where the tax code was correct, the tax may have been properly collected.
Does the S0T Tax Code Affect National Insurance?
S0T determines how Income Tax is calculated through PAYE. It does not directly determine National Insurance contributions.
National Insurance is calculated under separate rules using the relevant earnings, contribution category and payment period.
The same distinction applies to student loan repayments, postgraduate loans and pension deductions, although pension arrangements can independently affect taxable pay.
For example, an employee might have more Income Tax deducted because their tax code changes from S1257L to S0T, while their National Insurance calculation remains unchanged.
This is why examining only the final take-home salary does not always explain what has happened.
Ellen Milner of the Chartered Institute of Taxation also highlighted the interaction between Scottish Income Tax and UK National Insurance thresholds in her commentary on the 2026/27 tax changes.
Her analysis reinforces the importance of treating the two deductions separately rather than assuming that a Scottish PAYE code changes both.
Does Living in Scotland Mean You Must Have S0T?
No. Living in Scotland normally means that Scottish Income Tax rules apply to your relevant employment and pension income, but it does not mean you should receive S0T specifically.
For many Scottish taxpayers with one employment and the full standard allowance, the usual code is S1257L.
S0T applies where the zero-allowance treatment is appropriate for that income source.
Scottish taxpayer status is primarily associated with the individual’s residence, not simply the physical location of the employer.
For example, someone who lives in Dundee but works remotely for a London employer may still be treated as a Scottish taxpayer.
Conversely, someone whose main home is in England does not automatically become a Scottish taxpayer because their employer has an office in Edinburgh.
HMRC considers the relevant statutory Scottish residence rules, particularly where an individual has homes in different parts of the UK or moves during the tax year.
What Should Employers Do When an Employee Has S0T?
Employers should ensure that Scottish tax codes are correctly implemented through their payroll systems.
Where HMRC has authorised S0T, payroll must apply the appropriate Scottish Income Tax bands and the specified cumulative or non-cumulative basis.
Employers should check that:
- The code entered in payroll matches the latest HMRC instruction.
- The employee’s Scottish prefix is retained.
- Week 1 or Month 1 indicators are applied where required.
- Employment starter and leaving information is submitted correctly.
- The appropriate deductions are reported through PAYE Real Time Information.
- Changes to tax codes are reflected in the correct payment periods.
An employer using 0T instead of S0T could calculate Income Tax using the wrong rates.
Likewise, SBR and S0T should not be treated as interchangeable simply because neither provides a Personal Allowance.
For businesses with employees across England, Scotland and Wales, correct payroll configuration is particularly important because different residence prefixes can result in different Income Tax calculations.
Frequently Asked Questions
What does S0T mean on my payslip?
S0T means Scottish Income Tax rates apply, with no Personal Allowance allocated to that job or pension.
Does S0T mean I am paying 40% tax?
No. S0T uses progressive Scottish Income Tax rates from 19% to 48%. The rate depends on the amount of taxable income.
Is S0T an emergency tax code?
Not automatically. S0T becomes an emergency or non-cumulative code when accompanied by markers such as W1, M1, X or NONCUM.
Is S0T normal for a second job?
It can be, particularly where the Personal Allowance is already allocated elsewhere. HMRC may also use other codes, depending on total income.
Can I change S0T to S1257L?
Only if S1257L is appropriate for your circumstances. HMRC must have accurate income and employment information before the correct code can be determined.
Will I get a refund if I have S0T?
A refund may be available if S0T caused you to overpay Income Tax. It is not guaranteed merely because the code appears on your payslip.
How long does it take HMRC to correct S0T?
HMRC generally aims to issue a corrected code within 15 working days once the relevant information has been updated, with payroll implementation following afterwards.
What is your reaction?