Transfer Tax Allowance to Spouse: UK Marriage Allowance Rules, Eligibility and How to Claim

Last Updated – 11-11-2026
Married couples and civil partners in the UK could reduce their combined Income Tax bill by up to £252 per year by transferring part of an unused Personal Allowance from one partner to the other.
This tax relief, known as Marriage Allowance, is particularly useful for households where one spouse earns less than the tax-free threshold and the other pays Income Tax at the basic rate.
For the 2026/27 tax year, an eligible person can transfer £1,260 of their Personal Allowance to their husband, wife or civil partner.
Couples who qualified in earlier years may also claim backdated tax relief worth up to £1,008 for the previous four tax years.
However, transferring tax allowance to a spouse does not automatically guarantee savings.
Our analysis of HMRC’s rules and professional tax guidance shows that the benefit depends on both partners’ incomes, their tax liabilities and whether the transferring partner needs some of the allowance being surrendered.
Understanding the calculation before making a claim can prevent unnecessary tax bills and help households secure the relief they are entitled to.
What Does It Mean to Transfer Tax Allowance to a Spouse?
Transferring tax allowance to a spouse means giving up a fixed portion of your Personal Allowance so your husband, wife or civil partner can receive a reduction in their Income Tax bill.
The arrangement is officially called Marriage Allowance.
Every eligible UK taxpayer normally receives a Personal Allowance of £12,570 for 2026/27. This is the amount of income they can generally receive before becoming liable for Income Tax.
Some people do not use their entire allowance because they work part-time, have a relatively small pension or receive limited taxable income.
Marriage Allowance allows one partner to surrender £1,260 of their allowance in exchange for tax relief for the other.
The key figures are:
| Marriage Allowance feature | 2026/27 amount |
| Standard Personal Allowance | £12,570 |
| Amount available to transfer | £1,260 |
| Personal Allowance remaining with transferring spouse | £11,310 |
| Maximum annual tax reduction | £252 |
| Maximum saving for current year and four previous years | £1,260 |
| Standard basic Income Tax rate | 20% |
The benefit is calculated as 20% of the amount transferred:
£1,260 × 20% = £252
The Low Incomes Tax Reform Group, which provides specialist guidance on taxation, makes an important technical distinction: the receiving spouse is granted a tax reducer rather than legally receiving a larger Personal Allowance.
This distinction matters when assessing eligibility, particularly if the receiving partner has very little Income Tax to pay.
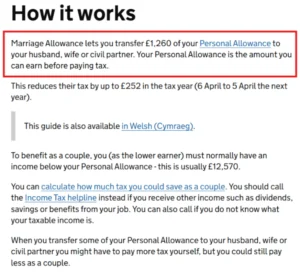
HMRC’s official Marriage Allowance guidance showing the £1,260 transferable allowance and maximum £252 annual tax saving.
Who Is Eligible to Transfer Tax Allowance to Their Spouse?
Marriage Allowance is available to married couples and civil partners who meet specific conditions.
Generally, the transferring spouse must earn less than their Personal Allowance, while the receiving spouse must pay Income Tax at the basic rate or an eligible Scottish rate.
The eligibility conditions include:
- The couple must be legally married or in a civil partnership.
- The transferring partner should normally have taxable income below £12,570.
- The receiving partner must not be liable to higher-rate or additional-rate Income Tax.
- Neither partner can receive Marriage Allowance and Married Couple’s Allowance simultaneously.
- Both partners must meet the relevant conditions for each tax year being claimed.
Couples who live together without being married or entering a civil partnership cannot claim.
Income Limits Across the UK
| UK country | Typical eligible income of receiving spouse in 2026/27 |
| England | £12,571–£50,270 |
| Wales | £12,571–£50,270 |
| Northern Ireland | £12,571–£50,270 |
| Scotland | £12,571–£43,662 |
These are typical thresholds for people with straightforward income and the standard Personal Allowance. Actual eligibility can differ when pension contributions, Gift Aid, savings, dividends or other income affect tax bands.
In Scotland, the receiving spouse must be liable only at the starter, basic or intermediate rates of Scottish Income Tax.
A Scottish taxpayer paying the higher, advanced or top rate is not eligible to receive Marriage Allowance.
HMRC also confirms that being retired or receiving pension income does not automatically disqualify a couple. The important consideration is their overall taxable income and applicable tax rates.
A useful distinction for working households: the lower earner does not need to be unemployed. Someone earning £9,000 from part-time employment could qualify just as readily as a spouse with no income, provided the other eligibility conditions are satisfied.
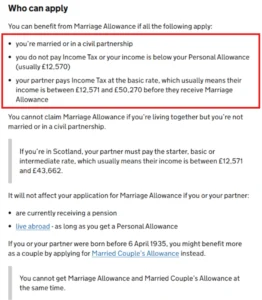
Official Marriage Allowance eligibility criteria showing the income limits for England, Wales, Northern Ireland and Scotland.
How Much Tax Can You Save by Transferring Your Allowance?
The maximum household saving is £252 a year, but the actual benefit depends on how much allowance the lower earner can afford to give up and how much Income Tax the receiving spouse owes.
Consider a couple where one partner earns £9,000 and the other earns £35,000 annually.
The lower earner has £3,570 of unused Personal Allowance, meaning surrendering £1,260 does not increase their tax liability.
The higher earner receives a £252 tax reduction.
The combined household therefore saves the full £252.
A different outcome occurs when the lower earner’s income approaches £12,570.
How the Savings Change at Different Income Levels?
The following calculations assume the receiving spouse earns £30,000 and can use the full £252 reduction.
Both partners are subject to standard England, Wales or Northern Ireland Income Tax rates, with no additional taxable income or adjustments.
| Lower earner’s annual income | Additional tax paid by lower earner | Tax reduction for spouse | Net household saving |
| £9,000 | £0 | £252 | £252 |
| £11,000 | £0 | £252 | £252 |
| £11,500 | £38 | £252 | £214 |
| £12,000 | £138 | £252 | £114 |
| £12,500 | £238 | £252 | £14 |
These examples highlight why eligibility and financial benefit are not necessarily the same thing.
When a spouse transfers £1,260, their own Personal Allowance reduces from £12,570 to £11,310.
If their income exceeds £11,310, some previously tax-free income may become taxable.
Financial guidance from the Low Incomes Tax Reform Group specifically warns that some couples can become worse off if they claim without assessing both individuals’ liabilities.
For straightforward basic-rate taxpayers, the maximum benefit will generally arise when the transferring spouse earns £11,310 or less and the receiving spouse has at least £252 of Income Tax liability available to reduce.
Can Transferring Tax Allowance Actually Make a Couple Worse Off?
Yes. This is one of the most important considerations before claiming Marriage Allowance.
Take a hypothetical couple where:
- One partner earns £11,900.
- The other partner earns £12,950.
- Both have the standard £12,570 Personal Allowance.
Without Marriage Allowance, the lower earner pays no Income Tax and the higher earner pays £76.
If the lower earner transfers £1,260, their reduced allowance becomes £11,310. They would now owe £118 in Income Tax.
Meanwhile, the receiving spouse can only use £76 of the potential £252 tax reduction because that is their total Income Tax liability.
Their new combined tax bill becomes £118 instead of £76.
The household is £42 worse off.
The remaining £176 of the receiving spouse’s theoretical tax reduction is not paid out as a cash refund.
This demonstrates why couples should calculate their combined tax liabilities rather than focusing only on the advertised £252 saving.
It also explains why changes in pension income, part-time employment or retirement can affect whether an existing Marriage Allowance claim remains worthwhile.
How Do You Transfer Tax Allowance to Your Spouse Through HMRC?
The application is free when made directly through HMRC.
For a straightforward current-year claim, the person transferring the allowance should normally apply.
Step 1: Check Whether Both Partners Qualify
Confirm that you are married or in a civil partnership and that the person receiving the relief is not paying Income Tax at an ineligible higher rate.
Review both partners’ expected annual taxable income rather than relying exclusively on monthly take-home pay.
Step 2: Gather the Required Information
The application normally requires both partners’ National Insurance numbers.
The person applying must sign into the HMRC service and may need to verify their identity.
Step 3: Submit the Application
Visit the official HMRC Marriage Allowance service and select the application option.
Follow the instructions and provide the requested details.
HMRC’s online service normally sends an email confirming receipt of the application within 24 hours.
Step 4: Wait for Hmrc to Update Your Tax Arrangements
HMRC may apply the relief by changing the relevant PAYE tax codes or through Self Assessment.
Tax-code updates can take up to two months.
If the application is accepted during the current tax year, the changes normally take effect from the beginning of that tax year.
Step 5: Review Your Payslip or Tax Calculation
Check that the new tax code or Self Assessment calculation reflects the Marriage Allowance correctly.
If you normally receive the standard tax-free allowance, understanding how the code changes is easier when you know how an ordinary 1257L tax code works.
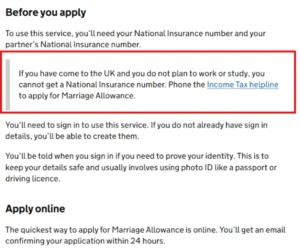
HMRC’s Marriage Allowance application instructions showing the information required before applying.
Can You Backdate a Marriage Allowance Claim for Previous Tax Years?
Yes. HMRC allows eligible couples to backdate Marriage Allowance claims for up to four previous tax years.
As of November 2026, the earliest tax year available for a new backdated claim is 2022/23.
| Tax year | Maximum available tax saving |
| 2022/23 | £252 |
| 2023/24 | £252 |
| 2024/25 | £252 |
| 2025/26 | £252 |
| 2026/27 (current year) | £252 |
| Total potential benefit | £1,260 |
The £1,260 figure represents the maximum combined benefit across five tax years. It does not mean everyone is entitled to a £1,260 cash refund.
The current-year relief may be delivered through reduced Income Tax deductions, while qualifying previous-year claims can result in repayments.
Each tax year is assessed separately. A couple who qualified in 2022/23 but became ineligible in 2023/24 cannot automatically claim both years.
An important deadline is 5 April 2027. This is the final date for an eligible claim relating to 2022/23 under the normal four-year repayment limit.
HMRC’s current postal procedure requires form MATCF for claims submitted by post. The form can be obtained through the Marriage Allowance guidance on GOV.UK.
People who paid too much tax can also encounter repayments through HMRC’s separate tax reconciliation process. Our explanation of when HMRC issues P800 tax refunds covers that process, although a P800 is not the required application form for Marriage Allowance.
HMRC’s Marriage Allowance backdating guidance confirming claims from the 2022/23 tax year and the MATCF postal application procedure.
What Do the M and N Tax Codes Mean After Transferring Marriage Allowance?
When HMRC processes a Marriage Allowance claim, it normally adjusts the PAYE tax codes of the individuals involved.
The receiving spouse’s code usually ends in M, while the transferring spouse’s code usually ends in N.
| Tax code example | Meaning |
| 1257L | Standard £12,570 Personal Allowance |
| 1383M | Illustrative code for the spouse receiving Marriage Allowance |
| 1131N | Illustrative code for the spouse transferring Marriage Allowance |
| S1383M | Illustrative Scottish recipient code |
| C1383M | Illustrative Welsh recipient code |
These are simplified examples. Actual codes may differ because of taxable benefits, unpaid tax, other adjustments or the allocation of allowances across multiple income sources.
The receiving spouse’s PAYE code can appear to represent an additional £1,260 tax-free allowance, even though the legal mechanism is a tax reduction.
For employees in Wales, the relevant tax code may also carry a C prefix. The explanation of C1257L and Welsh Income Tax codes provides useful background on how these regional prefixes work.
If a new code appears incorrect, contact HMRC rather than asking your employer to make an unauthorised adjustment.
Can Self-Employed People Transfer Their Personal Allowance?
Self-employed individuals may qualify for Marriage Allowance just like employees, provided their tax circumstances meet the requirements.
The main difference is how the tax relief is administered.
People registered for Self Assessment may need to claim Marriage Allowance through their tax returns instead of using the standard online application.
HMRC instructs the person transferring their allowance to complete the Marriage Allowance section of their Self Assessment return.
The spouse receiving the relief should leave that particular section blank.
If both partners file Self Assessment returns, HMRC advises that the transferring spouse should submit theirs at least three days before the receiving spouse submits theirs.
This helps HMRC recognise the transfer before calculating the recipient’s tax liability.
The order can matter for business owners, sole traders and others whose tax affairs are managed through Self Assessment.
In practice, self-employed people should also consider whether their trading profits may rise before the tax year ends.
A sole trader expecting £10,000 of taxable profit could initially appear able to transfer the full allowance without any personal tax cost. However, an unexpected increase in profits could push their income above £11,310, reducing the household’s net benefit.
The relevant figure is taxable income after appropriate tax calculations, not simply business turnover.
For people with fluctuating earnings, it may be sensible to calculate the expected year-end position before making a claim.
Can Company Directors, Landlords and Pensioners Claim Marriage Allowance?
Different sources of income can affect eligibility, and the calculations may be more complicated than they first appear.
Company directors: A director receiving a modest PAYE salary may appear to have unused Personal Allowance. However, dividends and other taxable income must also be considered. A salary below £12,570 does not necessarily mean the director is a non-taxpayer.
Landlords: Rental profits can form part of taxable income. Someone earning £9,000 from employment and receiving £5,000 of taxable rental profit cannot assess their eligibility using salary alone.
Pensioners: Receiving State Pension or private pension income does not automatically prevent a claim. However, taxable pension income must be included when calculating the transferring spouse’s available allowance and the receiving spouse’s tax liability.
For households approaching retirement, changing pension income can affect which spouse benefits from Marriage Allowance.
Someone considering whether to defer their State Pension should assess that decision separately, including its wider retirement implications, rather than treating Marriage Allowance as the deciding factor.
MoneyHelper also advises couples to consider both allowances and their circumstances when deciding which tax relief may apply. Its explanation of Marriage and Married Couple’s Allowance provides independent guidance.
For company directors with dividends, people receiving substantial savings interest or households with several taxable income sources, professional tax advice may be particularly valuable.
An additional technical issue is that income falling within a dividend or savings allowance can still affect which tax band applies for Marriage Allowance eligibility. The absence of a tax charge on a particular dividend does not, by itself, establish that the recipient qualifies.
What Happens to Marriage Allowance When Your Income Changes?
Marriage Allowance normally continues automatically each tax year until it is cancelled.
This makes it convenient for households whose finances remain stable, but potentially problematic when their circumstances change.
Changes worth reviewing include a partner returning to full-time employment, receiving a salary increase, starting a profitable business, taking a pension, receiving new taxable investment income or becoming liable to higher-rate tax.
Where the couple no longer satisfies the eligibility rules, HMRC requires the allowance to be cancelled.
If the reason is a change in income, the cancellation normally takes effect from the end of the current tax year.
If the marriage or civil partnership ends, cancellation may be backdated to the beginning of the tax year.
Either person can cancel where the relationship has ended. For other reasons, the person who originally made the claim must normally cancel it.
Simply leaving the Marriage Allowance section blank on a Self Assessment return does not cancel an existing claim.
If the tax treatment changes retrospectively, one partner may discover that insufficient tax has been paid.
The practical approach is to review the allowance whenever either partner’s financial position changes significantly.
Is Marriage Allowance Different From Married Couple’s Allowance?
Yes. Although their names are similar, the two tax reliefs have different eligibility conditions and potential benefits.
Marriage Allowance is primarily aimed at couples where one partner has unused Personal Allowance and the other is an eligible taxpayer.
Married Couple’s Allowance is an older relief for couples where at least one spouse or civil partner was born before 6 April 1935.
| Feature | Marriage Allowance | Married Couple’s Allowance |
| Main qualifying factor | Eligible married or civil-partnered couple | At least one partner born before 6 April 1935 |
| Maximum tax reduction in 2026/27 | £252 | £1,170 |
| Income conditions | Receiving partner must not be a higher-rate taxpayer | Different rules and income-related restrictions |
| Can both allowances be claimed together? | No | No |
Married Couple’s Allowance can reduce the annual tax bill by between £453 and £1,170 in 2026/27, subject to individual circumstances.
Couples who meet the age conditions should compare the two reliefs before claiming.
Will the Marriage Allowance Change in 2027?
The UK Government’s November 2026 Budget rates and allowances publication confirms that the Marriage Allowance transfer amount will remain at £1,260 for the 2027/28 tax year.
The standard Personal Allowance is also listed as £12,570 for 2027/28.
Under the confirmed figures, the maximum annual Marriage Allowance tax reduction remains £252.
| Tax allowance | 2026/27 | 2027/28 |
| Standard Personal Allowance | £12,570 | £12,570 |
| Marriage Allowance transfer | £1,260 | £1,260 |
| Maximum Marriage Allowance tax reduction | £252 | £252 |
The unchanged allowance has a practical implication for households.
As earnings and other taxable income rise while the Personal Allowance remains fixed, some lower earners may use more of their allowance and therefore receive a smaller net household benefit from transferring it.
For example, a person earning £11,000 can currently transfer £1,260 without generating additional Income Tax on that salary. If their income rises to £12,000, the same transfer could create £138 of personal Income Tax liability at a 20% rate.
This does not necessarily make Marriage Allowance unsuitable, but it reduces the advantage.
Couples should reassess eligibility and the expected saving in each new tax year rather than assuming the previous year’s outcome will remain unchanged.
What Are the Most Common Mistakes When Claiming Marriage Allowance?
The rules are relatively straightforward for couples with stable employment income, but several mistakes can lead to a reduced benefit or an incorrect claim.
One is assuming that any unused Personal Allowance can be transferred. The Marriage Allowance transfer is a fixed £1,260 for 2026/27, not an individually chosen amount.
Another is using take-home pay instead of taxable income. Net pay can be affected by pension contributions, National Insurance and other deductions, none of which should simply be treated as equivalent to the Income Tax calculation.
Couples can also make errors by ignoring investment income, assuming the tax break applies to unmarried partners or overlooking changes that make the receiving spouse a higher-rate taxpayer.
Perhaps the most avoidable mistake is paying an unnecessary fee to a claims company.
HMRC does not charge for a direct Marriage Allowance application. Commercial refund services may deduct a fee or percentage from repayments.
The Low Incomes Tax Reform Group has warned taxpayers to be careful when dealing with tax refund companies, particularly where a commercial application service could be mistaken for HMRC itself.
Applicants should use the official government service and review any communication carefully before disclosing personal information.
Frequently Asked Questions
Can I transfer my full £12,570 Personal Allowance to my spouse?
No. Marriage Allowance permits a fixed transfer of £1,260 for 2026/27. It does not allow an individual to transfer their entire £12,570 Personal Allowance to another person.
Can I transfer tax allowance if my husband earns £50,000?
Potentially, yes. For an employee in England, Wales or Northern Ireland with straightforward taxable income of £50,000 and no other income or adjustments, the receiving spouse would generally remain within the basic-rate band.
Both partners must still satisfy the remaining conditions.
Can I claim Marriage Allowance if I have no income?
Yes. A person with no taxable income may be able to transfer £1,260 of their Personal Allowance to an eligible spouse or civil partner. The other partner must have sufficient Income Tax liability to use the relief.
Can we claim Marriage Allowance in the year we get married?
Yes. Marriage Allowance can generally be available for the full tax year in which the marriage or civil partnership takes place, provided the relevant conditions are satisfied.
Can I claim Marriage Allowance after my spouse has died?
In some circumstances, yes. HMRC allows claims involving a deceased spouse or civil partner, subject to the relevant eligibility and backdating rules. Applicants should contact HMRC’s Income Tax helpline for the appropriate procedure.
Can I transfer tax allowance to my wife if she earns more than £50,270?
Not ordinarily where she is liable to higher-rate Income Tax. However, pension contributions, Gift Aid and other adjustments can affect tax-band calculations. Eligibility should therefore be assessed using the relevant tax rules rather than gross salary alone.
Does Marriage Allowance affect National Insurance contributions?
Marriage Allowance is an Income Tax relief. It does not directly reduce an employee’s National Insurance contributions or transfer their National Insurance allowances.
What is your reaction?