When Do You Pay 40 Tax in the UK? Higher Rate Tax Threshold Explained

Last Updated: 03.11.2026
You normally start paying 40% Income Tax when your annual income exceeds £50,270 in England, Wales or Northern Ireland, assuming you receive the standard Personal Allowance.
For the 2026/27 tax year, income from £50,271 up to £125,140 falls within the higher-rate band.
However, crossing £50,270 does not mean your whole salary is taxed at 40%. Only the portion of your taxable income that falls within the higher-rate band is charged at 40%.
Income within lower bands continues to be taxed at the relevant lower rate.
The exact point at which higher-rate tax affects you can also depend on your Personal Allowance, pension contributions, employment benefits and other taxable income.
Understanding how much you can earn before paying tax can therefore be useful when looking at your overall tax position rather than salary alone.
How Much Can You Earn Before Paying 40% Tax?
For most taxpayers in England, Wales and Northern Ireland, you can have total income of up to £50,270 before any of it enters the 40% higher-rate band, provided you qualify for the full £12,570 Personal Allowance.
The threshold works by combining the £12,570 Personal Allowance with the £37,700 basic-rate band.
This means:
- First £12,570: Normally Tax-Free
- £12,571 To £50,270: Normally Taxed At 20%
- £50,271 To £125,140: Normally Taxed At 40%
- Above £125,140: Normally Taxed At 45%
These figures apply to the 2026/27 tax year for taxpayers in England, Wales and Northern Ireland. Scotland has different Income Tax rates and bands.
UK Income Tax Rates And Thresholds For 2026/27
The standard Income Tax position for someone receiving the full Personal Allowance is:
| Income Band | Income | Tax Rate |
| Personal Allowance | Up To £12,570 | 0% |
| Basic Rate | £12,571 To £50,270 | 20% |
| Higher Rate | £50,271 To £125,140 | 40% |
| Additional Rate | Over £125,140 | 45% |
The current tax year runs from 6 April 2026 to 5 April 2027. The Personal Allowance remains £12,570.
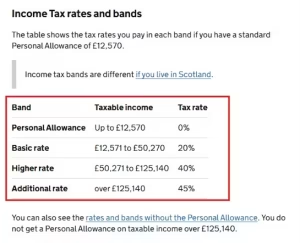
GOV.UK confirms the £12,570 Personal Allowance and the 20%, 40% and 45% Income Tax bands applying in 2026/27.
How Does The 40% Tax Bracket Work?
UK Income Tax uses marginal tax bands. This means different portions of your income can be taxed at different rates.
Someone earning £60,000 does not pay 40% tax on £60,000. Assuming they receive the standard Personal Allowance:
- £12,570: Taxed At 0%
- Next £37,700: Taxed At 20%
- Remaining £9,730: Taxed At 40%
Income Tax on the £60,000 salary would therefore be approximately £11,432, before considering pension arrangements or other adjustments.
Do You Pay 40% Tax On Your Entire Salary?
No. Entering the higher-rate tax band does not suddenly make your entire salary subject to 40% Income Tax.
If your salary increases from £50,270 to £51,270, for example, the additional £1,000 is normally the portion charged at 40%.
Your Personal Allowance and basic-rate portion continue to receive their respective tax treatment.
This distinction is important when considering pay rises, bonuses or overtime because moving into the higher-rate band does not usually leave you worse off simply because you crossed the threshold.
What Income Counts Towards The 40% Tax Threshold?
Your salary is not necessarily the only income considered when determining which tax bands apply.
HMRC’s calculation of taxable and adjusted net income can include several different income sources.
These can include:
- Employment Income: Salary, wages and taxable employment benefits
- Bonuses And Overtime: Additional taxable payments from your employer
- Self-Employment Profits: Taxable profits from sole-trader or freelance work
- Rental Income: Taxable property profits
- Pension Income: Most private, workplace and State Pension income
- Savings Interest: Interest above any relevant tax-free allowances
- Dividend Income: Dividends can affect your tax band although separate dividend tax rates apply
- Foreign Income: Certain taxable overseas income
This means somebody earning £48,000 from employment could still become a higher-rate taxpayer if they receive sufficient additional taxable income from rental property, savings, self-employment or another source.
Dividend income is treated differently from salary for the rate actually charged.
In 2026/27, dividends above the £500 Dividend Allowance are generally taxed at 10.75% for basic-rate taxpayers, 35.75% for higher-rate taxpayers and 39.35% for additional-rate taxpayers.
Examples Of 40% Tax At Different Salary Levels
The following simplified examples assume the individual lives in England, Wales or Northern Ireland, has the standard £12,570 Personal Allowance and has no other taxable income or deductions.
£55,000 Salary
At £55,000:
- £12,570: Tax-Free
- £37,700: Taxed At 20% = £7,540
- £4,730: Taxed At 40% = £1,892
Total Income Tax is approximately £9,432.
£60,000 Salary
At £60,000:
- £12,570: Tax-Free
- £37,700: Taxed At 20% = £7,540
- £9,730: Taxed At 40% = £3,892
Total Income Tax is approximately £11,432.
£75,000 Salary
At £75,000:
- £12,570: Tax-Free
- £37,700: Taxed At 20% = £7,540
- £24,730: Taxed At 40% = £9,892
Total Income Tax is approximately £17,432.
£100,000 Salary
At exactly £100,000, someone who remains entitled to the standard Personal Allowance would broadly pay:
- £37,700 At 20%: £7,540
- £49,730 At 40%: £19,892
Total Income Tax is approximately £27,432.
The position changes once adjusted net income goes above £100,000 because the Personal Allowance starts to be withdrawn.
What Happens To Your Personal Allowance Above £100,000?
The standard Personal Allowance begins reducing once your adjusted net income exceeds £100,000.
HMRC removes £1 of Personal Allowance for every £2 of adjusted net income above £100,000.
The allowance is completely lost once adjusted net income reaches £125,140.
For example, someone with adjusted net income of £110,000 is £10,000 over the £100,000 limit.
Their Personal Allowance is reduced by £5,000, leaving an allowance of £7,570.
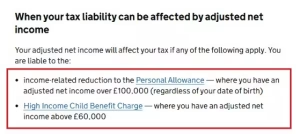
HMRC’s adjusted net income guidance confirms that the Personal Allowance is reduced when adjusted net income exceeds £100,000.
Why The £100,000 To £125,140 Range Can Create An Effective 60% Tax Rate?
The withdrawal of the Personal Allowance creates an unusual marginal tax effect.
For every additional £2 earned above £100,000, £1 of Personal Allowance is lost.
That £2 is taxed at 40%, while another £1 that would otherwise have been tax-free also becomes taxable at 40%.
As a result, the effective Income Tax rate on part of the income between £100,000 and £125,140 can reach 60%, before National Insurance or other deductions are considered.
What Changes When You Become A Higher Rate Taxpayer?
Paying higher-rate tax affects more than simply the rate charged on part of your salary.
Personal Savings Allowance
A basic-rate taxpayer can normally receive up to £1,000 of savings interest within their Personal Savings Allowance.
For a higher-rate taxpayer, this falls to £500. Additional-rate taxpayers do not receive a Personal Savings Allowance.
Moving just into the higher-rate band can therefore affect how much bank or building-society interest is tax-free.
Pension Tax Relief
Pension contributions can be particularly valuable for higher-rate taxpayers.
Where a pension uses relief at source, the pension provider normally claims basic-rate relief of 20%.
Someone who has paid Income Tax at 40% may then be able to claim an additional 20% tax relief, up to the amount of income on which they actually paid higher-rate tax.
Tax-efficient pension contributions are one of several tax-saving steps people may consider before the end of the tax year, although pension decisions should also consider annual allowance rules and individual financial circumstances.
High Income Child Benefit Charge
Becoming a higher-rate taxpayer does not automatically mean all Child Benefit has to be repaid.
For 2026/27, the High Income Child Benefit Charge can apply where adjusted net income exceeds £60,000 and either the individual or their partner receives Child Benefit.
The charge increases gradually between £60,000 and £80,000. At £80,000 or more, the charge can equal the full amount of Child Benefit received.
How Does National Insurance Work Alongside 40% Income Tax?
Income Tax and National Insurance are separate deductions.
For most employees paying standard Category A National Insurance in 2026/27, the employee rate is 8% on earnings within the main National Insurance band and 2% on earnings above the Upper Earnings Limit.
Because the Upper Earnings Limit broadly aligns with the £50,270 higher-rate Income Tax threshold, an employee earning above this point could typically face:
- Income Tax: 40%
- Employee National Insurance: 2%
- Combined Marginal Deduction: Around 42%
This is only a simplified figure. Student loan repayments, pension contributions, benefits and other deductions can change the amount actually taken from a payslip.
Do You Pay 40% Tax In Scotland?
No, not in the same way.
Scotland has its own Income Tax bands for earnings such as salary, pension income and self-employment profits.
For 2026/27, Scottish taxpayers have rates including:
| Scottish Tax Band | Rate |
| Starter Rate | 19% |
| Basic Rate | 20% |
| Intermediate Rate | 21% |
| Higher Rate | 42% |
| Advanced Rate | 45% |
| Top Rate | 48% |
For someone with the standard Personal Allowance, the Scottish higher rate of 42% broadly starts when total income exceeds £43,662, rather than at £50,270.
The advanced rate begins at £75,000 and the top rate applies above £125,140.
Scottish taxpayers can usually be identified by an S at the beginning of their tax code.
How Can You Legally Reduce The Amount Of Income Tax You Pay?
There is an important difference between legitimate tax planning and attempting to hide taxable income.
Depending on your circumstances, legitimate ways to reduce your Income Tax liability can include:
- Pension Contributions: Qualifying contributions can receive Income Tax relief
- Gift Aid Donations: Higher-rate taxpayers may be able to claim additional relief
- Allowable Employment Expenses: Certain qualifying work expenses can receive tax relief
- Available Allowances: Make appropriate use of tax-free allowances where eligible
- Correct Tax Code: Check that HMRC is applying the correct allowances and deductions
A taxpayer whose deductions suddenly increase should first check whether their tax code is correct.
Codes such as D0 can indicate that all income from a particular employment is being taxed at the higher rate, which may be appropriate where the Personal Allowance and basic-rate band are already being used elsewhere.
If too much PAYE has already been deducted, it may also be worth establishing whether HMRC owes a tax rebate rather than assuming the overpayment will always be refunded immediately.
Will The 40% Tax Threshold Increase In Future?
The £50,270 higher-rate threshold is not currently scheduled to increase in the near future.
The government has legislated to maintain the Personal Allowance at £12,570 and the basic-rate limit at £37,700, keeping the higher-rate threshold at £50,270 until 5 April 2031.
Keeping thresholds fixed while wages rise can cause more people to move into higher tax bands over time. This effect is commonly known as fiscal drag.
There is also an important change from 6 April 2027. The main higher rate applying to employment and pension income remains 40%, but the higher rates applying to savings and property income are scheduled to rise to 44%.
The corresponding basic rates for savings and property income will be 24%, while the additional rates will be 49%.
Conclusion
For most taxpayers in England, Wales and Northern Ireland, the answer to when do you pay 40 tax is when income moves above £50,270 during the 2026/27 tax year, assuming the standard Personal Allowance applies.
Crucially, only the part of income within the higher-rate band is normally taxed at 40%.
Reaching £50,271 does not cause your entire salary to be taxed at the higher rate.
Your actual position can become more complicated where you have bonuses, rental income, dividends, savings interest, pension contributions, Child Benefit or income above £100,000. Scottish taxpayers also have completely different earned-income bands.
With the £50,270 higher-rate threshold currently frozen until April 2031, more taxpayers could find themselves entering higher-rate tax as earnings increase even without the threshold itself changing.
FAQs About When You Pay 40 Tax
When Do You Start Paying 40% Tax In The UK?
For 2026/27, most taxpayers in England, Wales and Northern Ireland start paying 40% Income Tax when total income exceeds £50,270, assuming they receive the standard Personal Allowance.
What Is The 40% Tax Threshold For 2026/27?
The higher-rate band normally starts at £50,271 and extends to £125,140. Income above £125,140 generally enters the 45% additional-rate band.
Do You Pay 40% Tax On Everything Over £50,270?
Only the portion of income above the higher-rate threshold is normally taxed at 40%. Income in the Personal Allowance and basic-rate bands keeps its lower tax treatment.
How Much Tax Do You Pay On A £60,000 Salary?
Someone earning £60,000 with the full standard Personal Allowance would pay approximately £11,432 in Income Tax for 2026/27, before National Insurance and other adjustments.
Can Pension Contributions Reduce 40% Tax?
Yes. Qualifying pension contributions can receive higher-rate tax relief, and some contributions can also reduce adjusted net income for relevant tax calculations.
Does Rental Income Count Towards The 40% Tax Threshold?
Taxable rental profits are generally included when calculating taxable income, so property income can push someone into a higher tax band even when their employment salary alone is below £50,270.
Why Am I Paying 40% Tax If My Salary Is Below £50,270?
Other taxable income, a second job, employment benefits, savings, rental income or a reduced Personal Allowance can affect the tax calculation. An incorrect or temporary PAYE tax code can also result in higher deductions, so the code should be checked with HMRC.
What is your reaction?